Dubai property taxes for German, Austrian and Swiss buyers
The UAE currently has no general annual property tax and no personal income tax on private rental income. Your overall tax exposure nevertheless depends on where you are tax resident, how you hold the property and how it is used. Buyers connected to Germany, Austria or Switzerland need advice covering both jurisdictions; this guide explains the questions to ask, rather than offering personal tax advice or promising a tax saving.
Key facts at a glance
- No general annual UAE property tax does not mean that buying and operating a property is free of charges.
- Private property investment and business activities require separate tax analysis.
- Germany’s UAE income tax treaty expired at the end of 2021; Austria and Switzerland have treaties with the UAE.
- Foreign income and assets may still need to be disclosed in your country of tax residence.
- Property ownership or a residence visa does not settle tax residence or remove the need for departure planning.
UAE taxation: distinguish taxes from ownership costs
For a privately held apartment, the UAE starting point is currently relatively straightforward: there is no general recurring annual property tax comparable to that found in many European countries, and private rental income is not subject to personal income tax. That does not establish worldwide tax exemption. UAE corporate tax is a separate consideration: qualifying real estate investment by a natural person may be excluded, whereas a company or a licensed business activity needs its own assessment. Holiday accommodation, additional services and commercially organised operations deserve particular attention before you commit.
You still need to budget for registration and transaction charges, service charges, maintenance, management, insurance and any applicable municipal or usage-related fees. These are not the same as an annual property tax, but they reduce the cash available to you. VAT treatment also varies with the asset and the service supplied; residential accommodation, commercial premises and hospitality should not be grouped together. Request an itemised cost schedule rather than judging an investment by a tax-free headline. Our purchase costs guide provides useful financial context, without replacing a transaction-specific tax review.
Germany: residence and the expired tax treaty
If you remain subject to unlimited German income tax liability, foreign income generally remains within Germany’s tax framework. Receiving Dubai rent into a UAE bank account does not in itself remove that income from German consideration. The previous Germany–UAE double taxation agreement expired on 31 December 2021. You should therefore not rely on an exemption described in older treaty-based advice. Ask your adviser to verify the treaty position for the actual assessment year and apply the relevant German rules for foreign-source income. The location of the asset and the location of the bank account are different questions from your tax residence.
The German tax calculation is not necessarily the same as cash received or the yield shown in a sales brochure. Acquisition costs, attributable expenses, financing, depreciation and currency conversion must be considered under the applicable German rules. On disposal, the holding period, actual use and any business classification may matter. Relief for foreign tax requires an appropriate legal basis and qualifying tax actually incurred; an overseas investment does not generate a tax credit merely because it is located abroad. Commission a German after-tax assessment, identify the documents needed to support it, and retain a clear record of the assumptions used.
Austria: a treaty does not automatically mean exemption
Austria currently has a double taxation agreement with the UAE. For Austrian-resident buyers, the crucial issue is not simply whether a treaty exists, but how its current relief provisions operate. Following amendments, the Austrian side generally needs to consider the credit method. The statement that Dubai rents are always exempt in Austria because a treaty exists is therefore not a sound planning assumption. Where there is no creditable UAE tax, Austrian tax may remain payable. An Austrian adviser should establish the relevant effective dates, the classification of the income and the precise application of the treaty to your circumstances.
You should also discuss how the rental activity is classified under Austrian principles, which expenses can be recognised and what evidence supports the investment forecast. Personal occupation, prolonged vacancy and a switch to holiday letting can raise different issues from a conventional long-term tenancy. Buying through a company is not a neutral substitute for personal ownership: it can change the income category, filing requirements and the treatment of later distributions. Compare structures against your wider assets and intended use, rather than selecting one on the basis of a general statement about Dubai. A useful analysis should explain both annual administration and the consequences of eventual disposal.
Switzerland: disclosure, progression and cantonal analysis
Switzerland also currently has a double taxation agreement with the UAE. For Swiss-resident individuals, foreign real estate and related income are generally considered through the international tax allocation framework. They are often exempt from direct Swiss taxation while remaining relevant to the applicable tax rate. That distinction does not mean that disclosure is unnecessary. The precise treatment must be confirmed against the treaty, cantonal practice and your personal circumstances. A calculation prepared for a German or Austrian resident cannot simply be reused after moving to Switzerland, even if the property, rental agreement and bank account remain unchanged.
Ask a Swiss specialist how to disclose the foreign property value, rental proceeds and any personal use. The allocation of debt and interest is equally important, as are potential effects on cantonal wealth taxation and rate determination. The purchase contract value or a figure supplied by a Dubai property manager is not necessarily the relevant Swiss tax value. Record the canton involved, the valuation approach and the supporting documents. This helps prevent a seemingly straightforward overseas investment from becoming an exercise in reconstructing values and occupancy periods when the annual return is due. Agree the reporting approach before handing the file to your accountant.
Organise reporting and supporting records from day one
An overseas property does not produce the same forms or notifications in every country. Distinguish rental income reporting from asset disclosure, notifications concerning company interests and bank requests for tax-residence documentation. Your adviser should set out which obligations actually apply to your ownership arrangement. Direct personal ownership can be treated differently from an interest in a foreign company. Transfers to family members, inheritance and eventual sale each deserve separate consideration. Do not assume that a Dubai manager will automatically satisfy your home-country obligations. Ask who is responsible for each filing, what information they need and when they need to receive it.
- Keep the purchase agreement, ownership evidence and transaction receipts together, with later amendments clearly linked.
- Record tenancy agreements, statements, receipts and vacancy periods consistently, keeping personal occupation separate.
- Provide finance agreements, interest statements and invoices for management or repairs to the relevant adviser.
- Agree a traceable currency-conversion method and regular data exports with the person preparing your returns.
- Maintain a shared annual schedule of responsibilities, individual filing deadlines and any changes in tax residence.
Moving to Dubai: residence and exit taxation are separate issues
Buying an apartment, obtaining a UAE residence visa or deregistering with a local authority does not automatically terminate tax liability in your former country. A home still available to you, actual presence, family connections and the centre of your personal and economic interests can all matter. A simple day-counting rule is therefore not a complete relocation plan. Have your intended departure reviewed using actual dates, accommodation arrangements and professional activities. Identify any income or other connections that will remain in the former country and could continue to create tax obligations. Residence analysis should describe what changes in practice, not merely which documents are obtained.
Exit taxation is a separate question. For certain shareholdings or other assets, a country’s loss of taxing rights can trigger taxation of unrealised gains even though no sale proceeds are received. Germany and Austria have different rules; Switzerland requires its own assessment by asset category and any business connection, rather than an imported German analysis. Not every private property buyer becomes subject to an exit charge merely by relocating. Entrepreneurs should nevertheless review company interests, effective management, business assets and funding needs before departure. Our relocation guide supports the practical preparations but is not a substitute for coordinated departure advice across jurisdictions.
Build an after-tax plan before exchanging contracts
Start with intended use and where you actually plan to live, rather than asking which property sounds tax-free. Compare realistic scenarios: remaining resident in your current country, relocating later, long-term letting, personal occupation or disposal. Each scenario needs its own income and expense forecast, supplemented by personal tax advice. Keep vacancy, repairs and management expenditure separate from tax so that the underlying economics remain visible. The aim is to understand whether the apartment still suits you if relocation is delayed or the intended use changes. A robust decision should not depend on a single optimistic assumption about your future residence.
Maximilian Popolari provides personal support through analysis, selection, purchase, handover and beyond. The property process supplies the asset, contract and operating information needed by your independent tax adviser; qualified tax professionals remain responsible for the tax conclusions. Our services also help coordinate responsibilities for letting, furnishing and eventual resale. Obtain the relevant tax review before making a binding purchase commitment. That review should consider not only the acquisition year, but the ongoing holding period and a plausible exit. Clear boundaries between property advice and tax advice make it easier to identify unanswered questions before they become expensive decisions.
Professional advice rather than blanket tax promises
Bring an overview of your assets, proposed financing, draft purchase agreement and living arrangements to the consultation. Ask the adviser to distinguish confirmed conclusions from assumptions and outstanding checks. Agree who will review subsequent changes, such as switching the letting model or moving your principal home. For property-specific preparation, you can arrange a personal consultation. We organise the real estate questions so your tax adviser can work from actual documents rather than indicative return claims. Keeping those documents current is just as important as obtaining advice before the initial purchase, particularly when your family or business circumstances change.
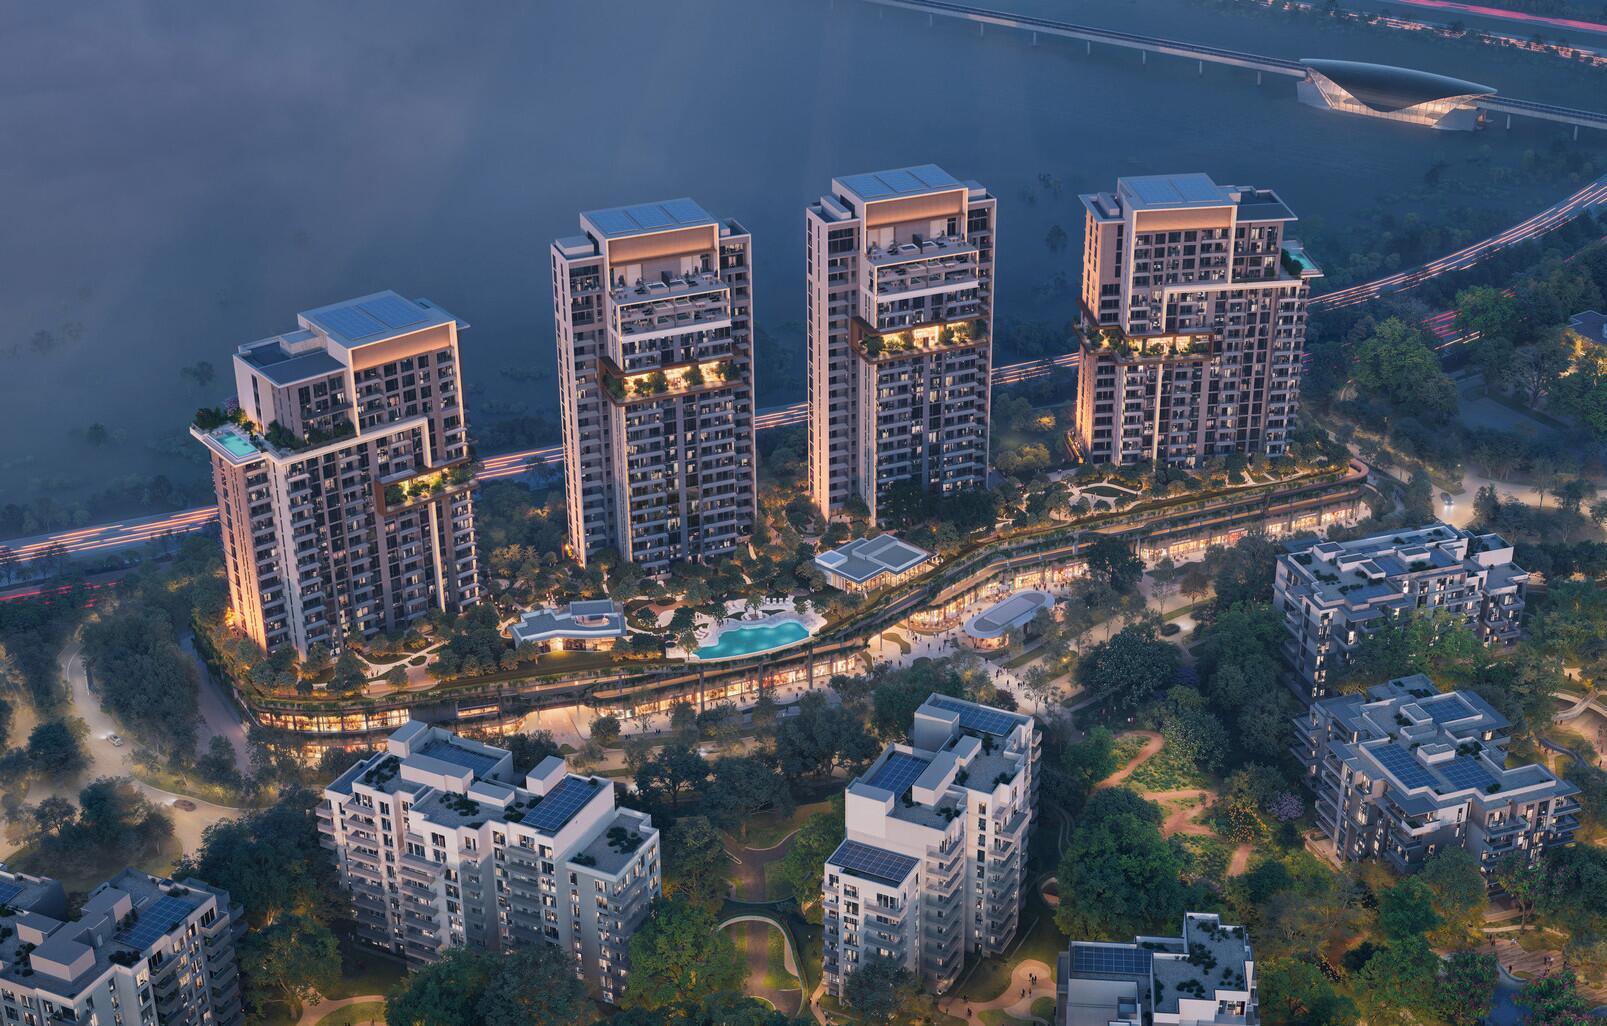
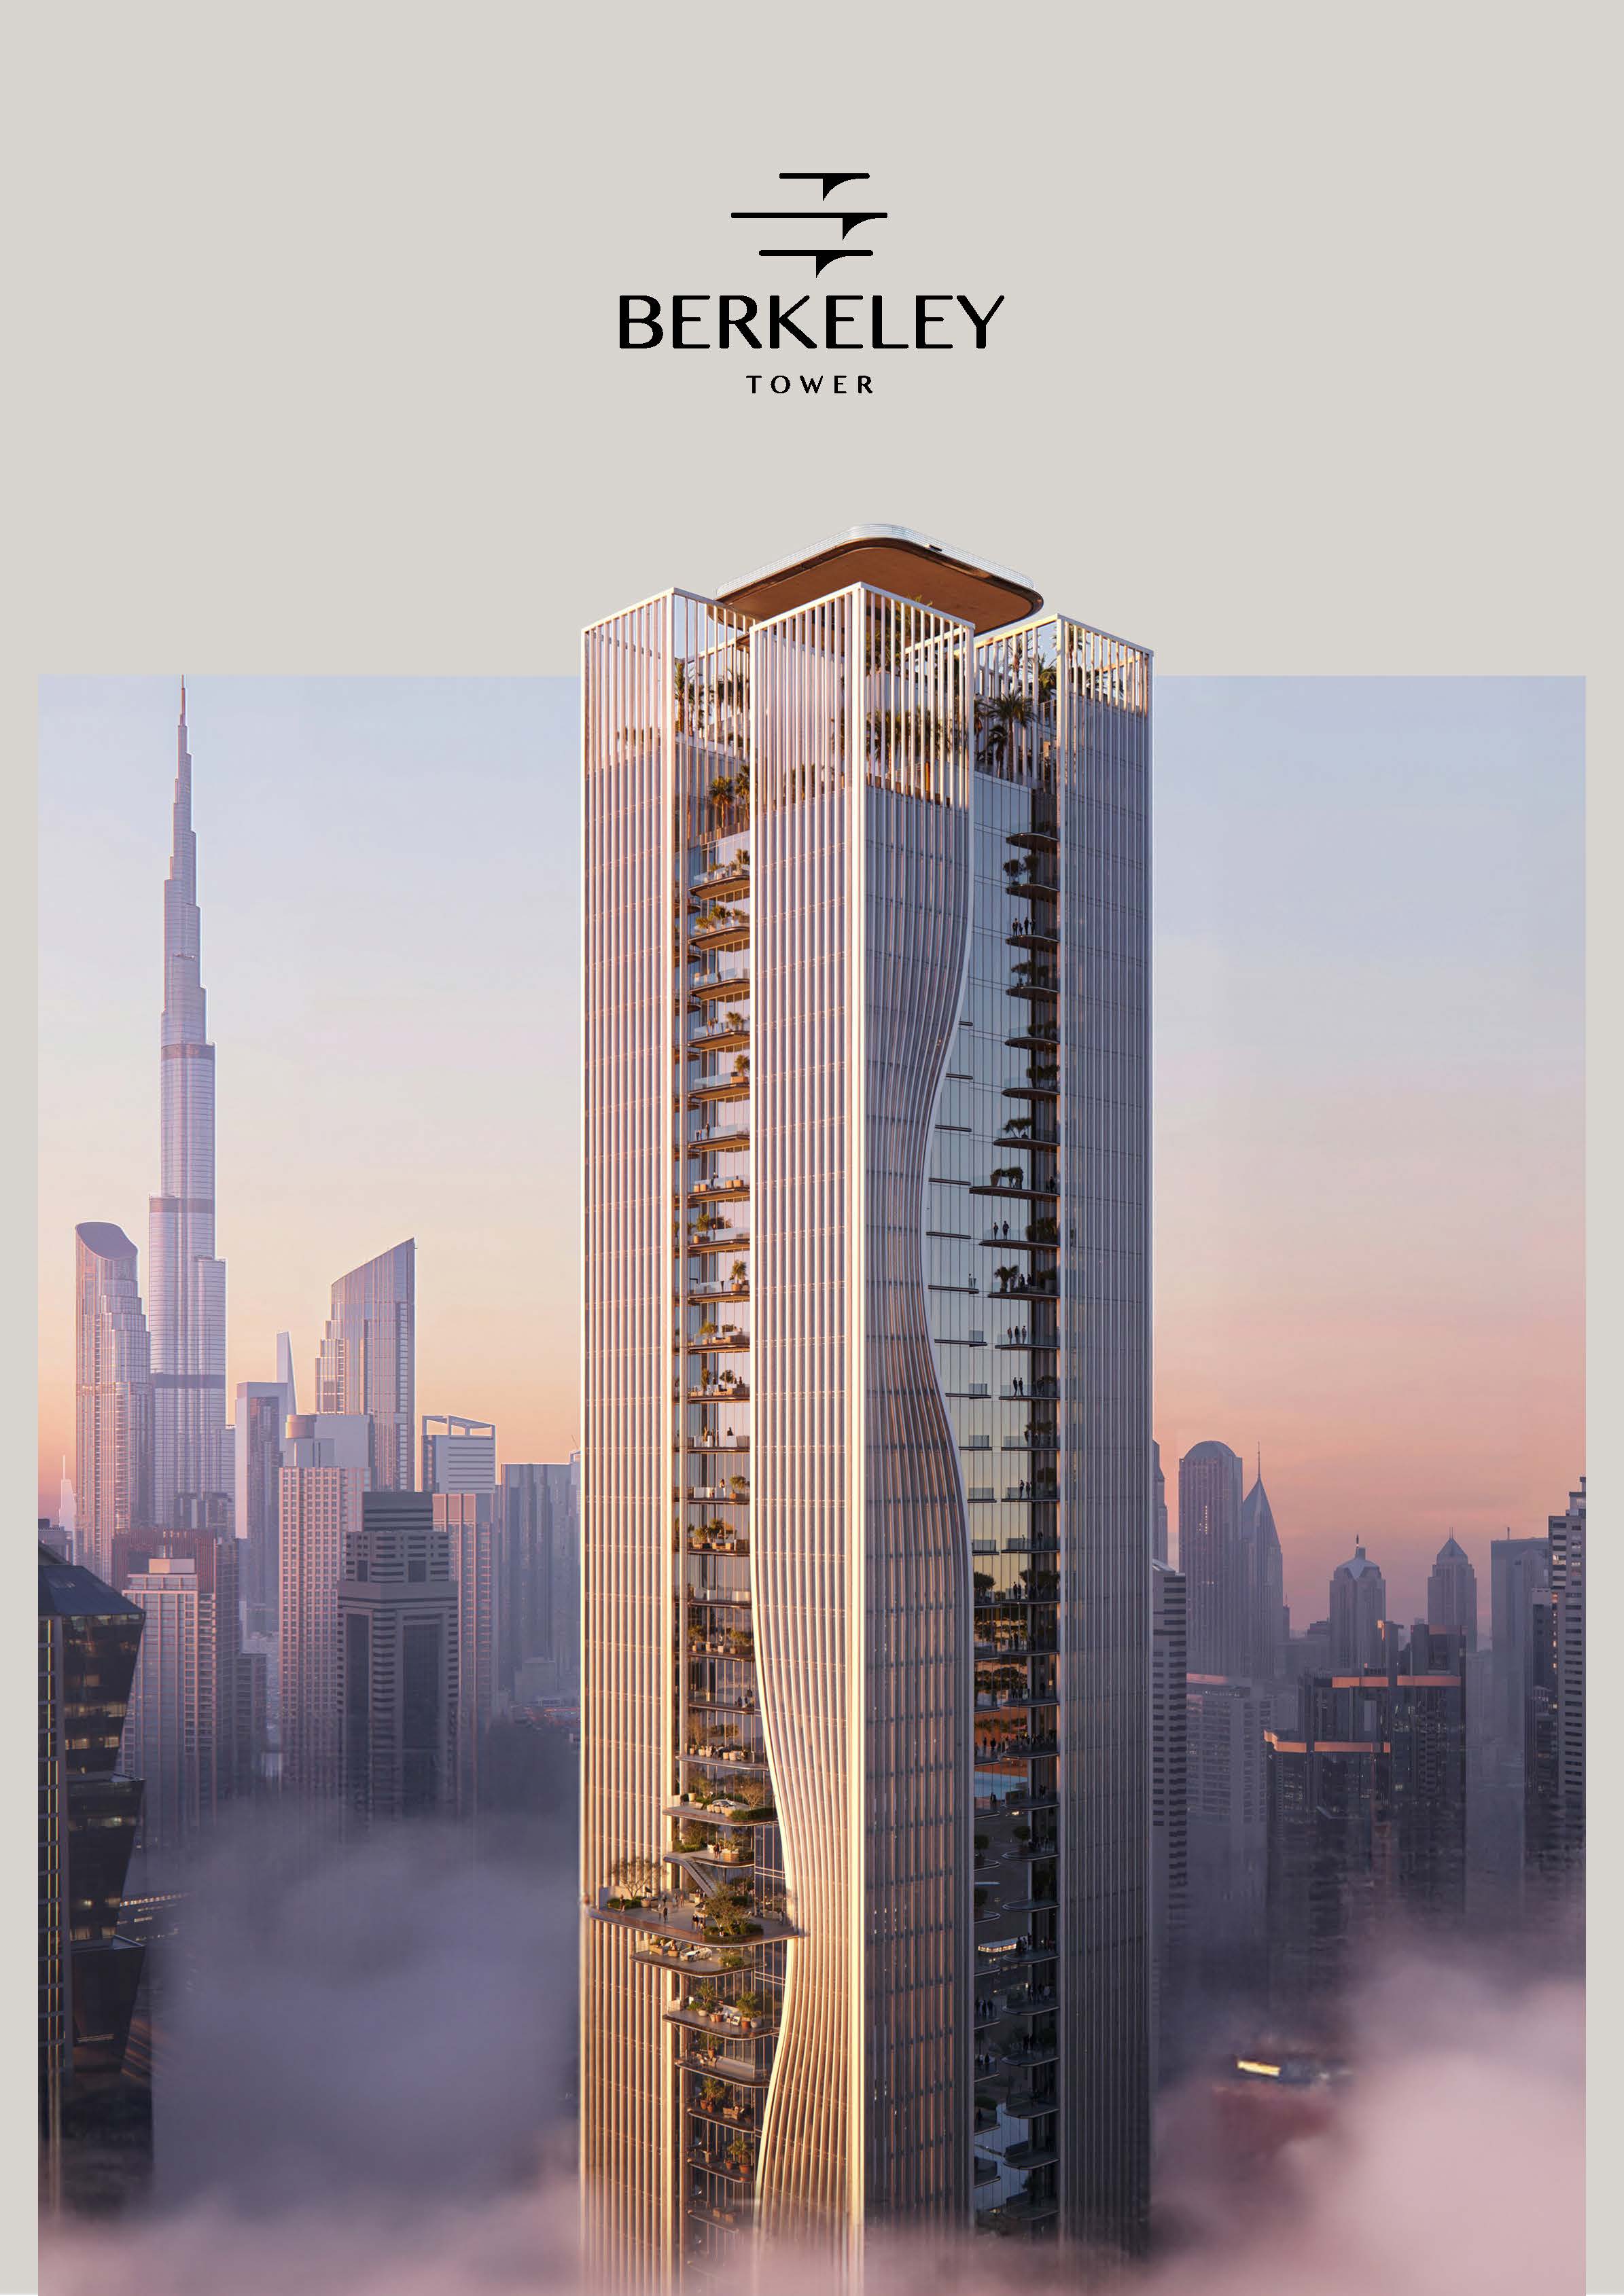
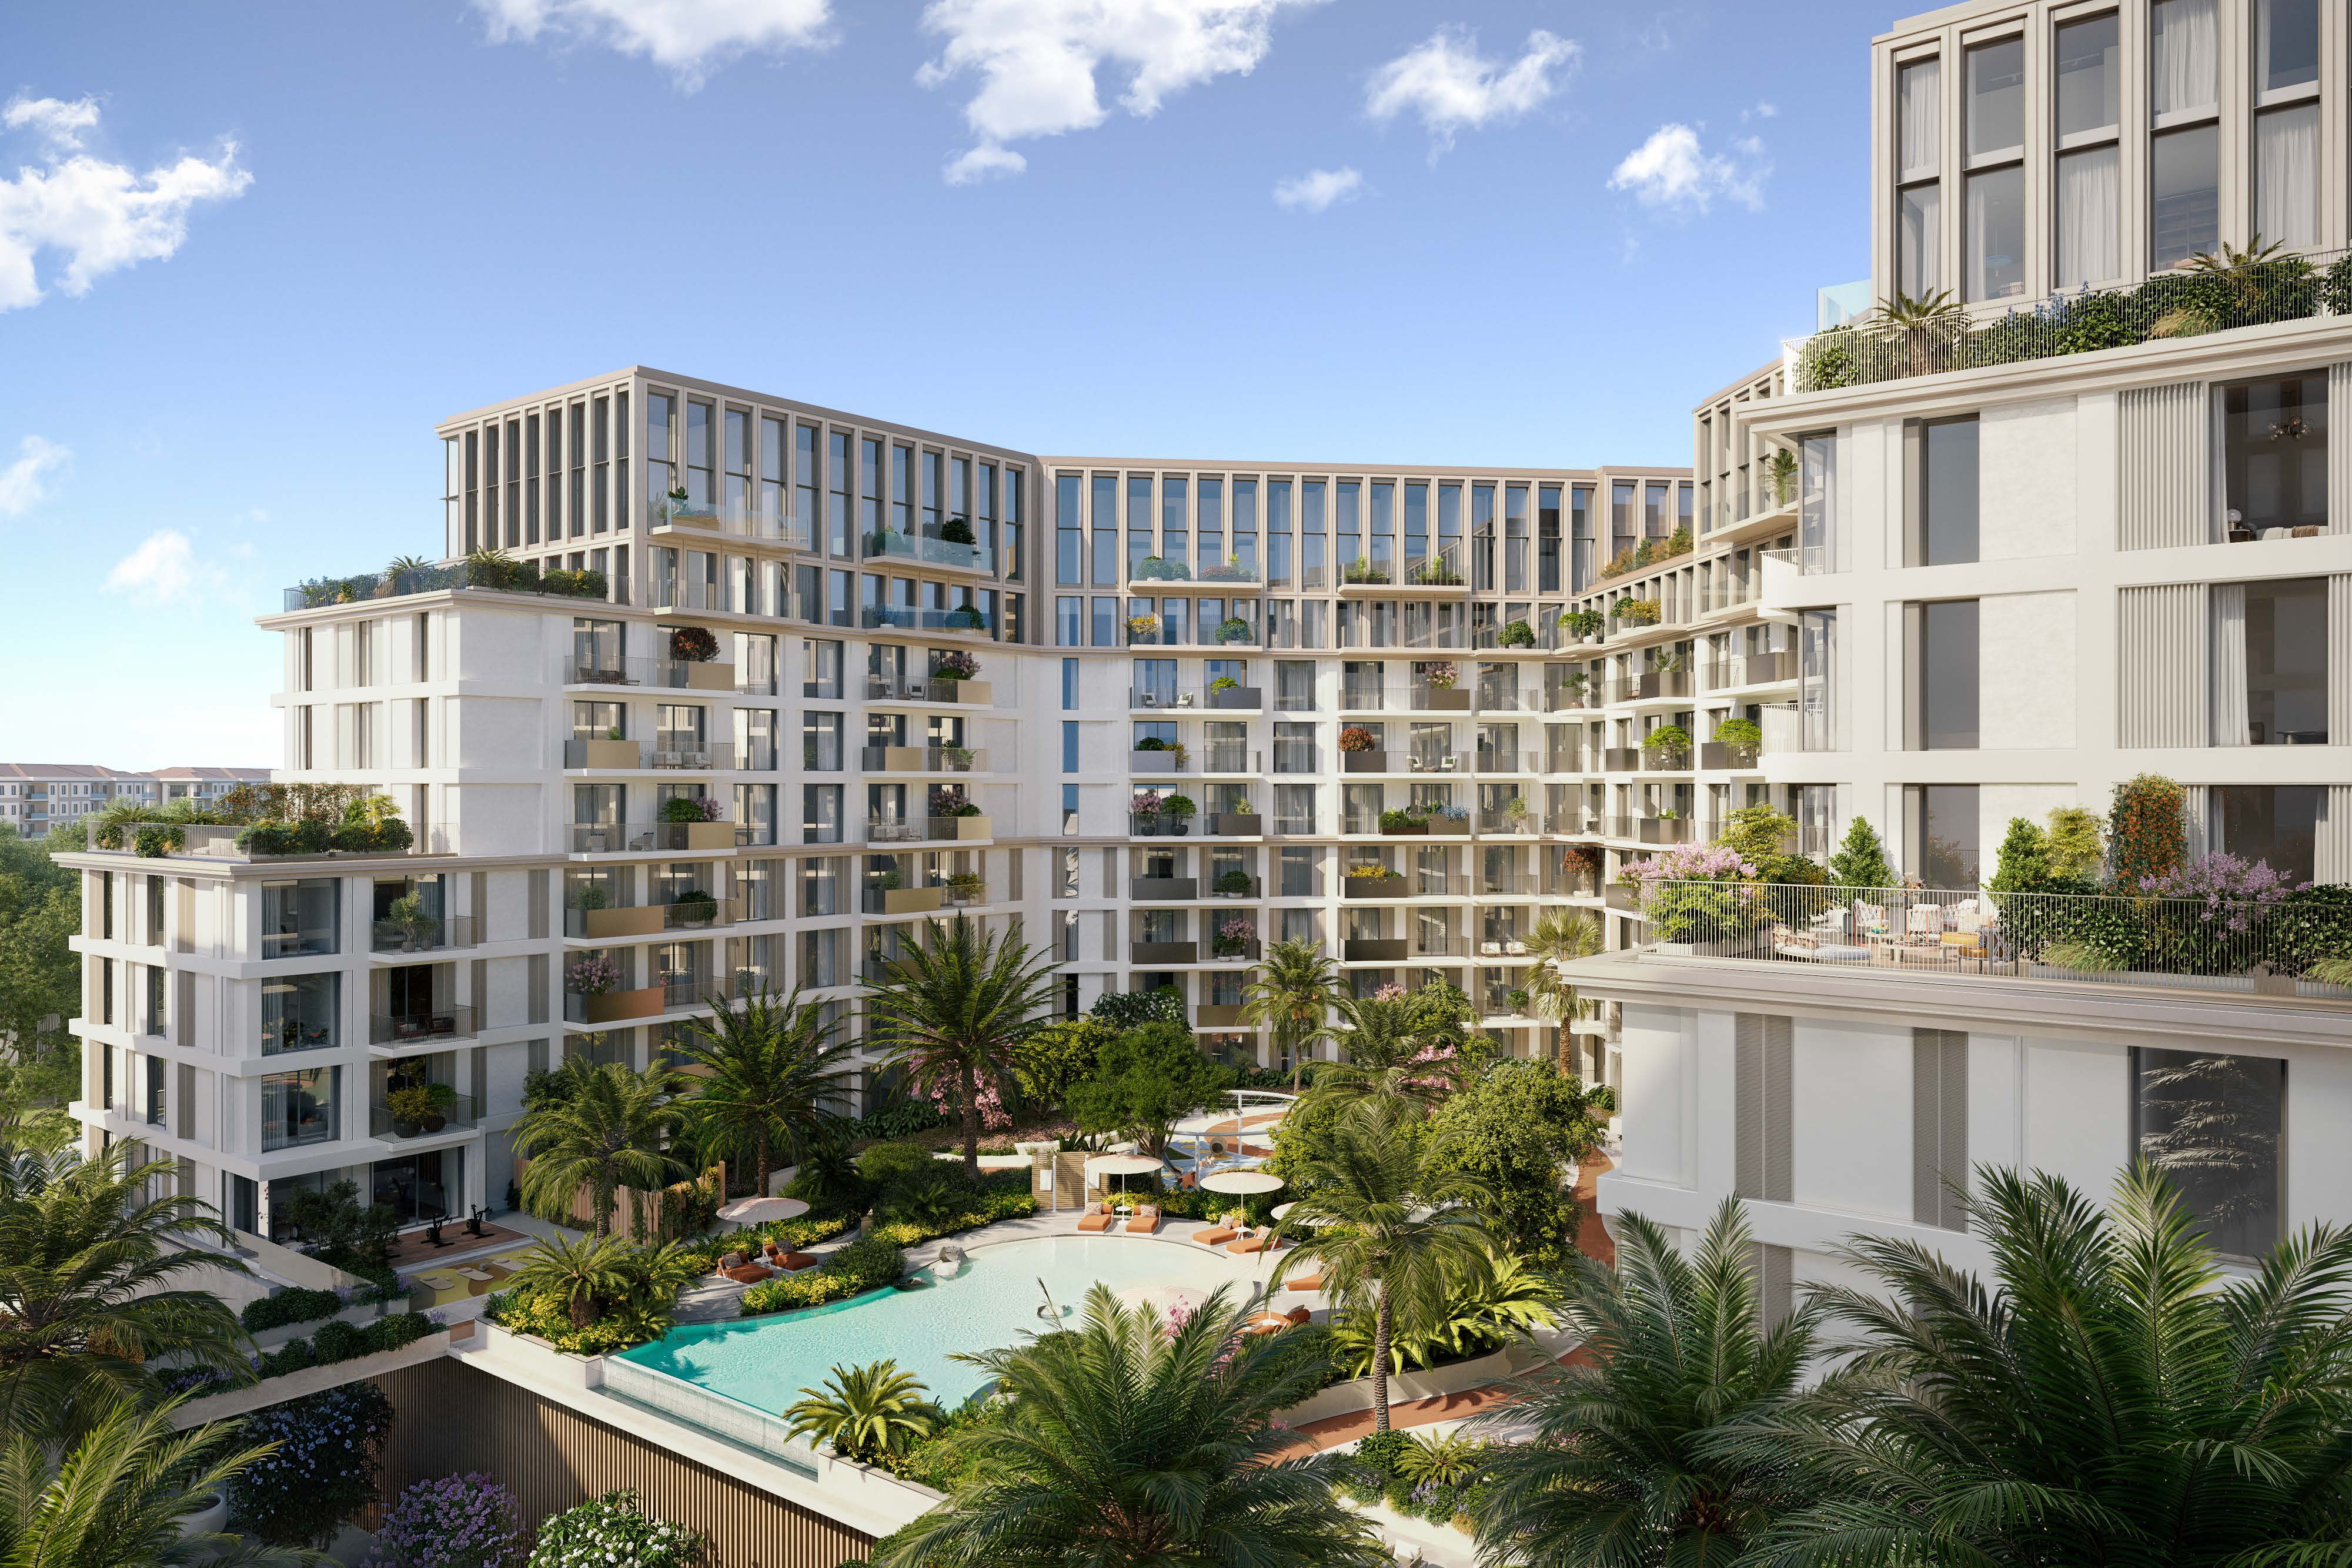
Matching projects from our portfolio
Personal advice
Your questions, straight to Maximilian.
Frequently asked questions
Will my Dubai rental income be tax-free?
Does Germany have an income tax treaty with the UAE?
Why do Austria and Switzerland require different analyses?
Does a Golden Visa end tax liability in my former country?
Which documents will my tax adviser need?
This article is for general information only and does not replace tax or legal advice.